S Corp Distributions Basis is the ceiling.
Cash that is not wages can leave free of a second tax only while basis remains. Past that, the tax life changes.
The ceiling, stated plainly.
Basis is the ceiling on cash that is not wages. Wages are not limited by that ceiling. They are pay, and they have their own reporting. Cash that is not pay can leave without a second tax only while basis remains. Past the ceiling, that cash has a different tax life. We say the ceiling exists. We do not teach the order of old earnings as a slogan.
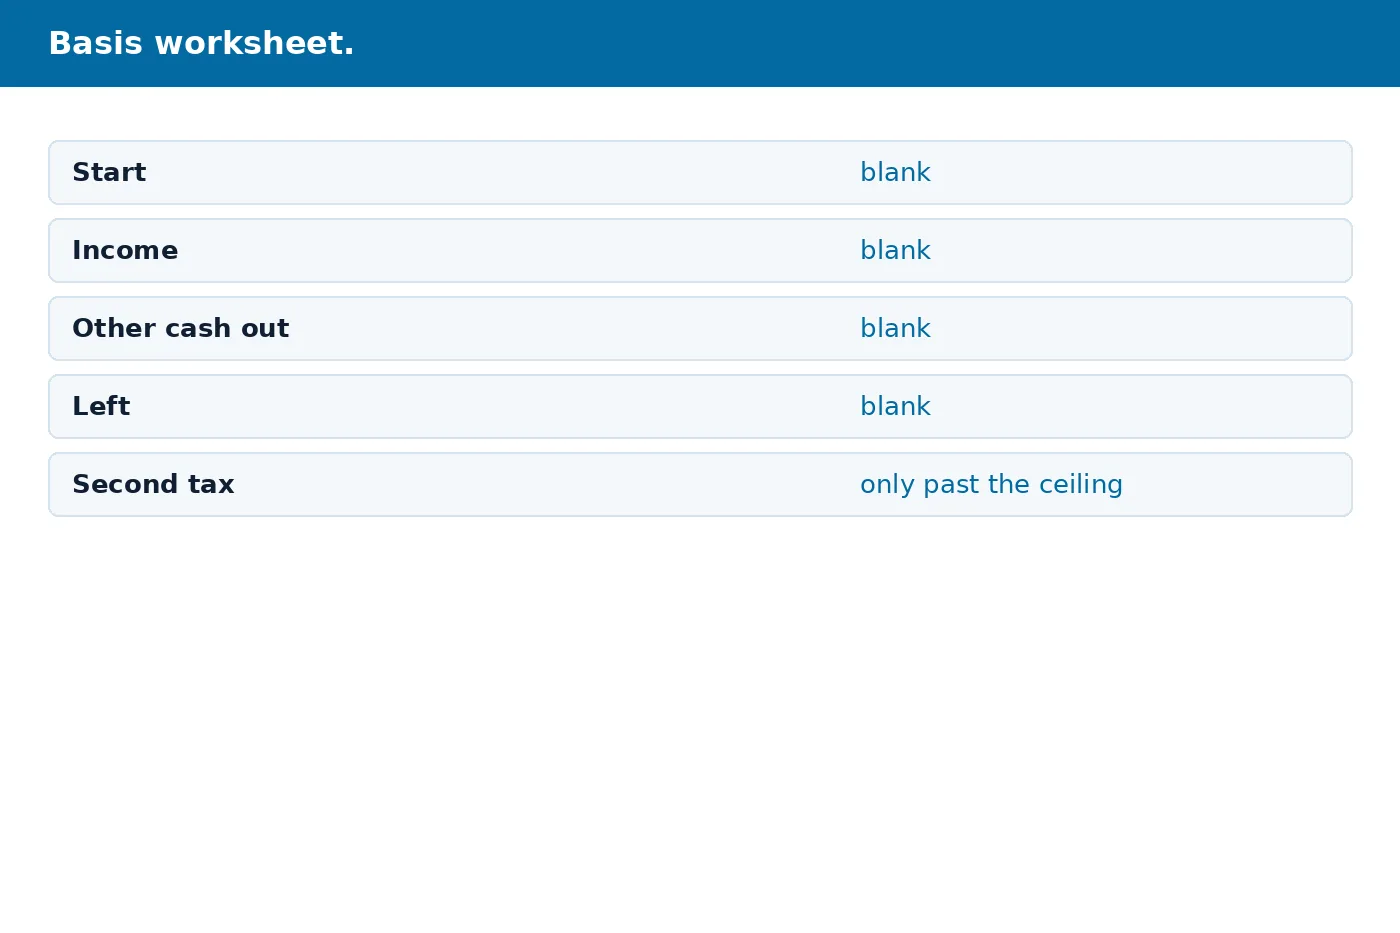
The federal worksheet for a shareholder's basis is Form 7203. We use it as a worksheet beside the books. We do not walk a visitor through line numbers on a public page, because the lines reward a careful reading with the file open and punish a summary that skips a box. When a paragraph of the instructions needs that reading, we do the reading inside the engagement.
Contributions and distributions are not netted into a single friendly number and then forgotten. Money in and money out are different events. The equity chart in the books keeps them apart so the worksheet has something true to sit on. The return does not contain a line called equity that replaces that work.
What adds, what uses it up.
Money the owner put in, and income that has passed through and been taxed already, are the usual ways the ceiling rises. Cash that left as something other than wages, and losses that passed through, are the usual ways it falls. That sentence is the shape. The order, the losses that were limited before, and the items that are not simple income are the part we re-read with the file. They are real. They are not a paragraph this page can safely compress into a proverb.
A year with profit and no cash taken can raise the ceiling and leave the bank alone. A year with cash taken and little profit can use the ceiling up. Owners feel the second year in the bank and miss it on the return. We put the worksheet next to the bank activity so the feeling and the form can disagree in public, where we can see it.
If the ceiling is already used up, we do not hunt for a loan costume. We say the cash has the other tax life, or we say the cash should not move until the facts change. Both answers are allowed. A invented note is not.
Books first, worksheet second.
A messy ledger makes a messy worksheet. If money in and money out share one account, the worksheet repeats the mix. We pull them apart before any number is claimed. A closed month, a bank reconciliation, and a chart that keeps the two directions separate come first. The worksheet follows.
The return follows the worksheet. An owner who wants the return first, and the ceiling afterward, is asking for a guess with a signature. We decline. Old months can still be cleaned when the records exist. The current month can be closed. Further cash that is not pay can wait until the ceiling is known.
Health premiums and wages affect the story too, because wages are not the cash this ceiling limits, and premiums for an owner over two percent ride on the wage line. The pages for wages and premiums sit beside this one. The loan temptation is on the loan page.
Ask about basis still left.
Say whether a worksheet exists. Do not send the worksheet here.
You will be talking to the Steven Palmieri practice.